How Annuity Agents Get Paid (Straight Talk)
Most people never ask how the person recommending their annuity gets paid. You should, and a good agent should answer without flinching. Here's how it works, including how I'm paid.
Most annuity agents are paid a commission
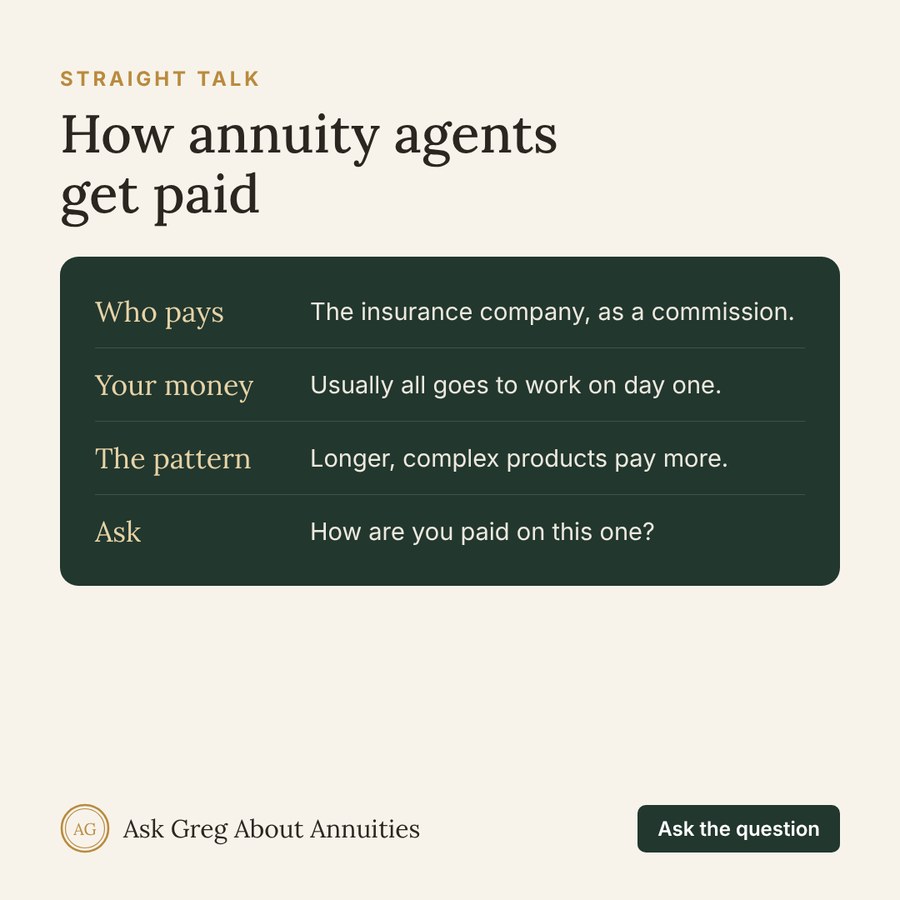
When you buy a fixed or fixed indexed annuity, the insurance company pays the agent a commission. That includes me. You don't write a separate check for it.
Does it come out of my money?
Not directly. With most fixed and fixed indexed annuities, every dollar you put in goes to work for you on day one. If you put in $100,000, your account starts at $100,000.
The company recovers the commission over time, through the rates it pays you and through the surrender charge if you leave early. That's one reason the surrender period exists.
Want to see how this applies to your money? I'll walk through your numbers on a free call, in plain English. Pick a time →
How much is it?
It varies a lot by product. Roughly speaking, shorter, simpler products like multi-year guaranteed annuities and income annuities tend to pay smaller commissions. Longer fixed indexed annuities, especially ones with long surrender periods or bonuses, tend to pay more. Commissions are often lower for older buyers.
The pattern matters more than the exact number: longer, more complex products usually pay the agent more.
Why it matters to you
A commission isn't bad by itself. Someone has to be paid to do the work, and fee-based advisors charge too, often a yearly percentage of your account. What matters is whether the recommendation fits you or fits the paycheck.
Be extra careful if you're steered toward a long surrender period you don't need, a bonus product when a simpler one would do, or swapping out an annuity you already own.
Questions to ask any agent
- "How are you paid on this?"
- "Would you be paid more or less on the other options you showed me?"
- "Why this surrender period instead of a shorter one?"
- "If I'm replacing an annuity, what am I giving up, and what would I pay to leave it?"
How I handle it
I'm independent, so I'm not required to sell any one company's products. I'll tell you how I'm paid on anything I recommend, and I'll show you simpler options next to more complex ones. And when the right answer is to leave your money where it is, I'll say so, even though I don't get paid for that advice.
Have a question about your own numbers?
Book a free call of up to 30 minutes. I'll give you a straight answer in plain English, including when the best move is to leave things where they are.
Book a free callFree guide: 5 questions to ask before you buy any annuity
A two-page checklist you can print and bring to any annuity conversation, with room for notes. Enter your email and it's yours.
No spam. I'll send an occasional plain-English note, and you can unsubscribe anytime. Privacy policy.