9 Red Flags in an Annuity Pitch
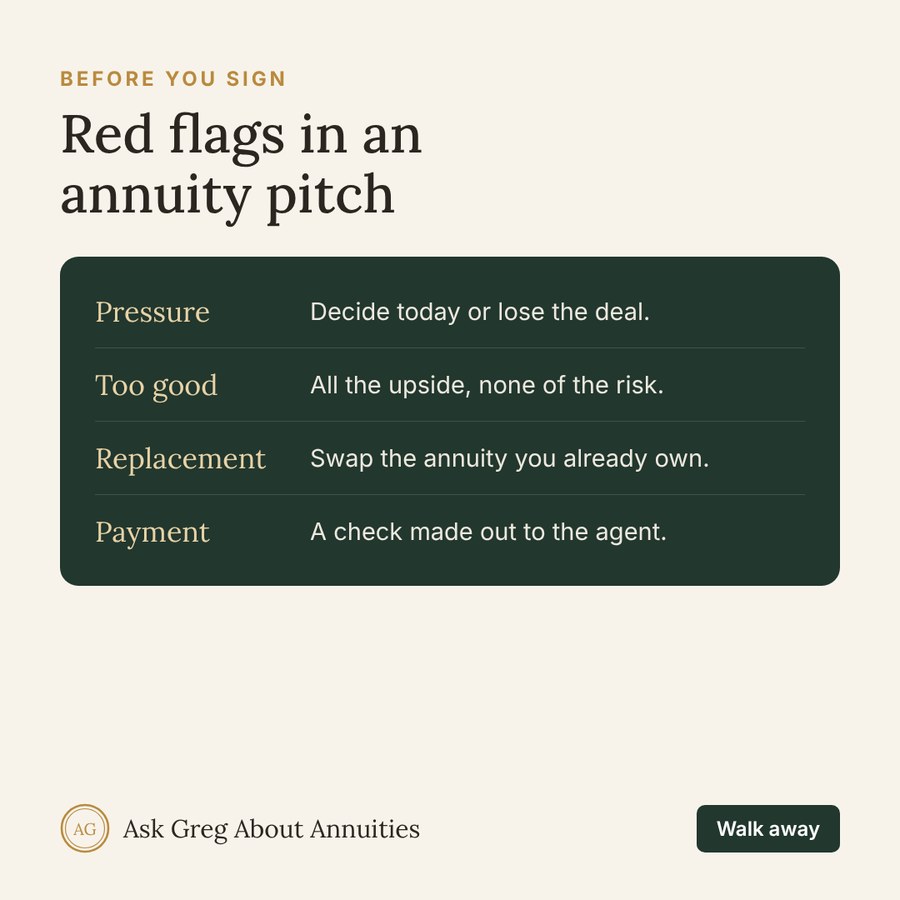
Most annuity agents are honest. A few aren't, and retirees are their favorite target. Here are the warning signs I'd want my own family to know.
1. Pressure to decide today
"This rate goes away Friday" or "I can only hold this bonus until tomorrow." A good decision about your retirement money can wait a week while you think, ask questions and talk to family.
2. The free lunch seminar
A free steak dinner isn't a crime. If the dinner leads to a one-on-one meeting where you're pushed to move money, slow down. The meal was paid for by the sale.
Want to see how this applies to your money? I'll walk through your numbers on a free call, in plain English. Pick a time →
3. "All the upside, none of the risk"
Fixed indexed annuities do protect you from market losses. In exchange, your gains are limited by caps or participation rates. Anyone who suggests you get stock market returns with no trade-off isn't telling you the whole story. Here's how they really work.
4. Putting all your money in one place
An annuity is a long-term contract with surrender charges. You need money outside it for emergencies and surprises. Be wary of anyone who wants nearly everything you have.
5. Replacing an annuity you already own
Sometimes switching makes sense. It's also how some agents earn a new commission at your expense: a new surrender period, lost benefits, and charges to leave the old one. How to check whether a switch makes sense.
6. Only the rosy numbers
If you're shown projections but not the guaranteed column of the illustration, ask for it. The guaranteed numbers are the only ones the company promises.
7. Fuzzy answers on fees and surrender charges
You should get the surrender schedule and every yearly fee in writing, before you sign. If the answer is "don't worry about that," worry about it.
8. A check made out to the agent
Your premium should always be paid to the insurance company, never to the agent or the agent's business. This one is a deal-breaker.
9. No license you can look up
Anyone selling annuities in Texas must hold a Texas insurance license. You can check any agent on the Texas Department of Insurance website. (Mine is #1291485.)
You have a free look
After you receive an annuity contract, you have a "free look" period to cancel and get your money back. The length depends on your state and situation, so check your contract. If something feels wrong after you sign, use it.
Not sure about a pitch you've been given? Bring it to me. I'll give you a straight read on it, even if the answer is "this one's fine."
Have a question about your own numbers?
Book a free call of up to 30 minutes. I'll give you a straight answer in plain English, including when the best move is to leave things where they are.
Book a free callFree guide: 5 questions to ask before you buy any annuity
A two-page checklist you can print and bring to any annuity conversation, with room for notes. Enter your email and it's yours.
No spam. I'll send an occasional plain-English note, and you can unsubscribe anytime. Privacy policy.