Is Your Old Annuity Still Working for You?
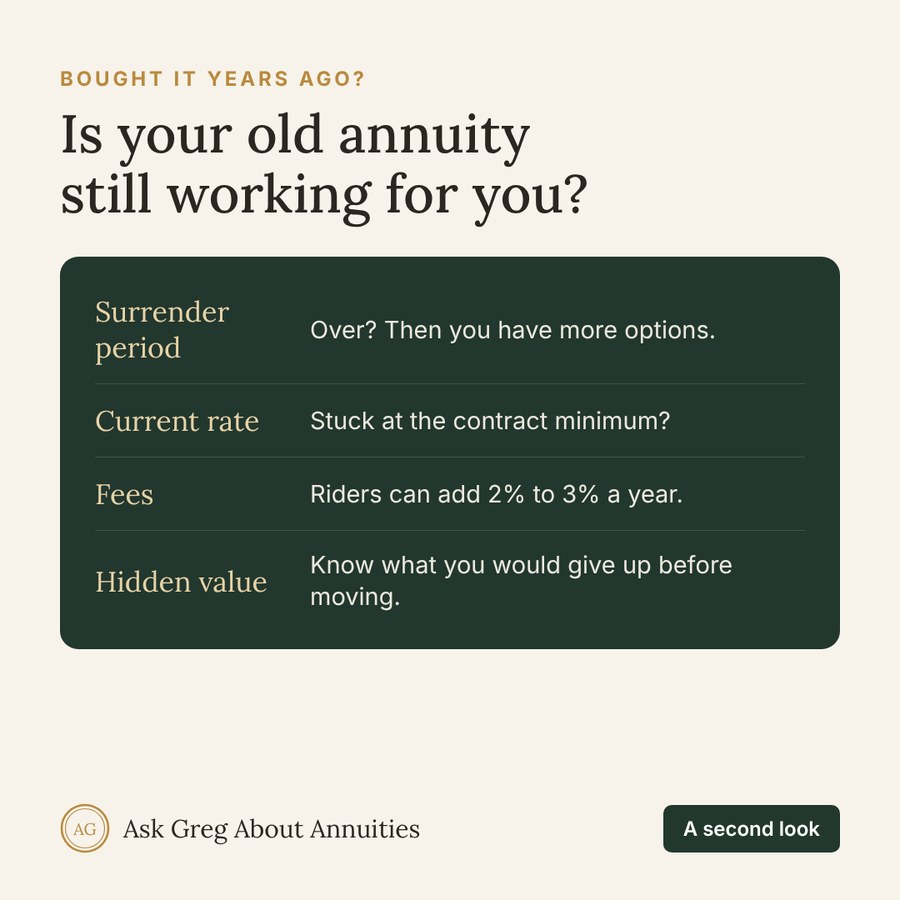
A lot of people own an annuity they bought years ago and haven't looked at closely since. Maybe the agent who sold it retired. Maybe you're just not sure what it's doing anymore. Here's how to check on it.
Start with your latest statement
Find these four things:
- Account value: what it's worth today.
- Surrender value: what you'd get if you cashed out today, after any surrender charge.
- Current rate: what it's earning now, for a fixed or indexed annuity.
- Fees: especially on a variable annuity, where yearly costs can run 2% to 3% or more once riders are included.
If the statement doesn't show something, call the company and ask. You own the contract, and they'll tell you.
Is the surrender period over?
If the account value and the surrender value are the same, your surrender period has ended. That gives you more options, because you can move the money without a penalty.
Want to see how this applies to your money? I'll walk through your numbers on a free call, in plain English. Pick a time →
Has the rate dropped?
Many older fixed annuities started with a decent rate that has since been lowered to the contract minimum, sometimes 1% to 3%. If yours is sitting at its minimum while newer products pay more, it may be worth a look.
Does it have a benefit you'd lose?
This is the big one. Some older annuities carry valuable features: a high guaranteed minimum rate, an income rider with a large "benefit base," or an enhanced death benefit. Those can be worth far more than the account value suggests, and they usually disappear if you move the money. Before changing anything, find out exactly what you'd be giving up.
What a 1035 exchange is
If moving makes sense, a 1035 exchange lets you transfer the money from one annuity to another without paying tax on the gains. The money goes company to company, so it never passes through your hands.
A new annuity usually starts a new surrender period. In Texas, the agent also has to give you a written comparison of the old and new contracts. Read it.
When to leave it alone
- It's still in its surrender period and the charge would wipe out the benefit of switching.
- It has a guaranteed rate or income benefit better than what's available now.
- You're close to needing the money and don't want a new surrender period.
- It's doing its job and you're comfortable with it.
Sometimes the best answer is to keep what you have. I'll tell you if that's the case. If you'd like a second look, bring me your latest statement and I'll go through it with you, in plain English.
Have a question about your own numbers?
Book a free call of up to 30 minutes. I'll give you a straight answer in plain English, including when the best move is to leave things where they are.
Book a free callFree guide: 5 questions to ask before you buy any annuity
A two-page checklist you can print and bring to any annuity conversation, with room for notes. Enter your email and it's yours.
No spam. I'll send an occasional plain-English note, and you can unsubscribe anytime. Privacy policy.