Building a Retirement Income Plan Around Your TRS Pension
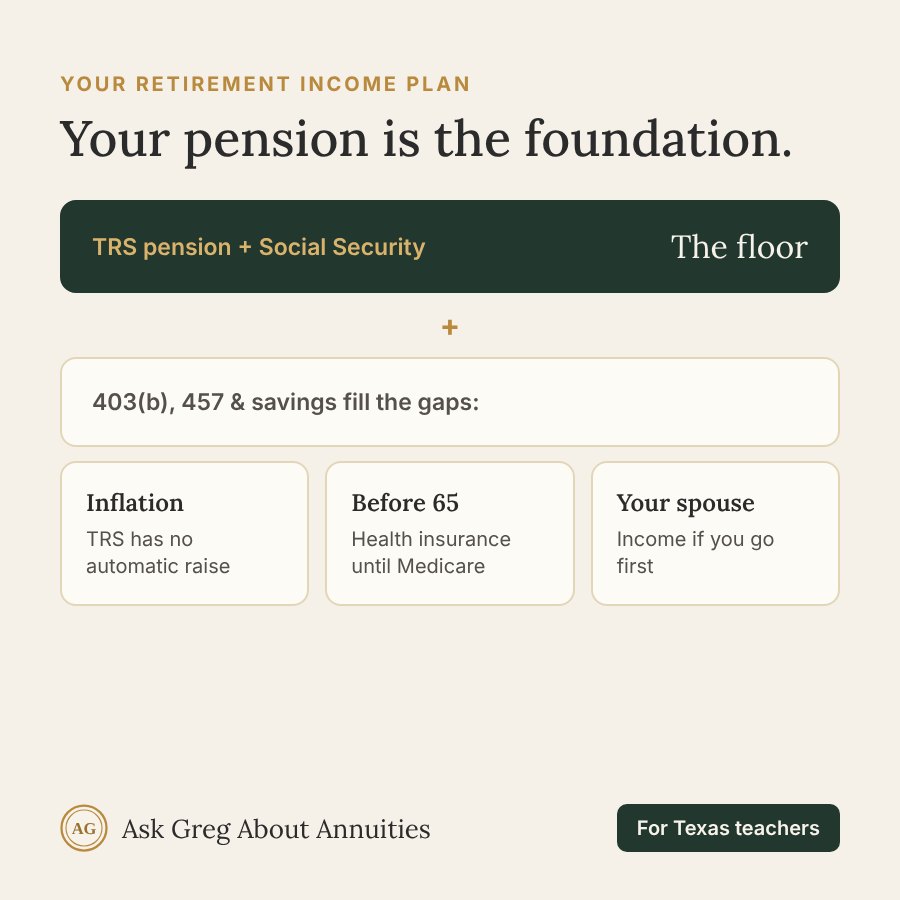
Short answer: start with what your TRS pension and Social Security will pay each month, figure out how much is left over, and use your 403(b), 457 and other savings to cover that gap and the things your pension won't: inflation, health insurance before Medicare, and a spouse.
Step 1: Start with your floor
Your TRS pension is income for life, and that's a big advantage most people don't have. Add any Social Security you'll receive. Thanks to the Social Security Fairness Act, that may be more than you expected. Together, that's your floor.
Step 2: Find your gap
Subtract that floor from what you'll spend each month. What's left is your monthly income gap, the amount your savings need to cover. For some teachers it's small, and for others it's bigger than they thought.
Step 3: Plan for what your pension won't cover
- Inflation. TRS has no automatic cost-of-living increase. Your savings need to grow to keep your buying power up over a long retirement.
- Health insurance before 65. If you retire before Medicare, budget for coverage, whether through TRS-Care or another plan, until you turn 65.
- Your spouse. If you take the standard TRS annuity, payments stop when you die. If your spouse depends on that income, compare the survivor options before you retire.
Want help putting the pieces together? I'll build a simple income plan with you on a free call. Pick a time →
Step 4: Give your savings the right job
Because your pension already gives you lifetime income, your savings usually have a different job than they would for someone without a pension:
- Keep an emergency cushion you can reach without penalties.
- Cover the gap between your floor and your essential bills, with steady, predictable income if that gives you peace of mind.
- Keep part of it growing so you can give yourself the raise TRS won't.
For many teachers, an annuity isn't needed at all, since the pension already does that job. For others, especially those with a big gap or a spouse to protect, guaranteed income for part of their savings makes sense. Either way, it's worth knowing which camp you're in. Here's when an annuity isn't the right answer.
Step 5: Time your Social Security
If you or your spouse qualify for Social Security, when you claim matters. Waiting raises your monthly benefit for life. With the WEP and GPO gone, it's worth running the numbers again.
General information, not tax or legal advice. Confirm pension details with TRS and Social Security details with the Social Security Administration.
Have a question about your own numbers?
Book a free call of up to 30 minutes. I'll give you a straight answer in plain English, including when the best move is to leave things where they are.
Book a free callFree guide: 5 questions to ask before you buy any annuity
A two-page checklist you can print and bring to any annuity conversation, with room for notes. Enter your email and it's yours.
No spam. I'll send an occasional plain-English note, and you can unsubscribe anytime. Privacy policy.