Why Retiring Into a Down Market Is So Risky
Here's a retirement risk that surprises a lot of people: two retirees can start with the same savings, earn the same average return, and end up in completely different places.
An example
Picture two people who each retire with $500,000 and take out $30,000 a year. Over twenty years, they get the exact same set of annual returns, averaging 3.75%. The only difference is the order those returns arrive in.
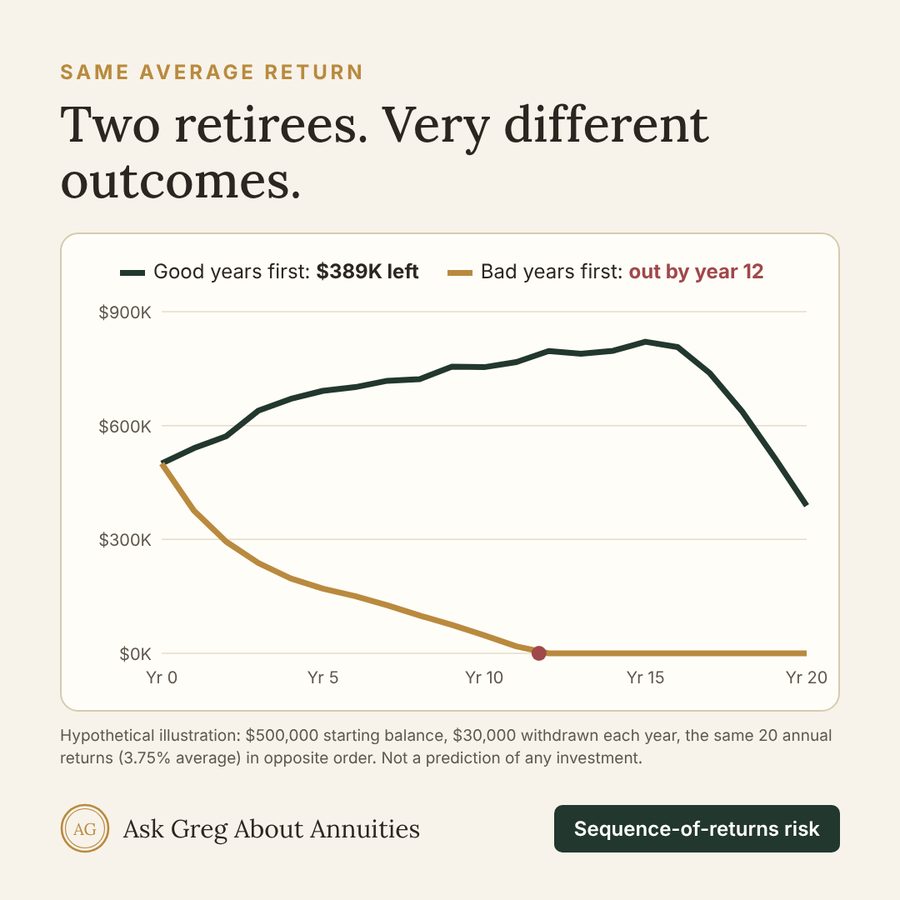
- Good years first: after twenty years, this retiree still has about $389,000.
- Bad years first: this retiree runs out of money in year twelve.
Why it happens
When the market drops early in retirement, you're selling investments at low prices to pay your bills. Those shares are gone, so they aren't there to recover when the market comes back. The same drop late in retirement does far less damage, because the account has already had years to grow.
This is called sequence-of-returns risk, and the years just before and just after you retire are when it matters most.
Want to see how this applies to your money? I'll walk through your numbers on a free call, in plain English. Pick a time →
How people manage it
- Cover the basics with steady income. Social Security, a pension, or an income annuity pays the bills no matter what the market does, so you aren't forced to sell in a downturn.
- Keep a cash cushion of one to two years of spending to draw from during a bad stretch.
- Be flexible about spending in down years when you can.
The first step is knowing how much of your monthly spending is already covered by steady income. That's your income gap.
Have a question about your own numbers?
Book a free call of up to 30 minutes. I'll give you a straight answer in plain English, including when the best move is to leave things where they are.
Book a free callFree guide: 5 questions to ask before you buy any annuity
A two-page checklist you can print and bring to any annuity conversation, with room for notes. Enter your email and it's yours.
No spam. I'll send an occasional plain-English note, and you can unsubscribe anytime. Privacy policy.